Market Review & Outlook
Market Review
Most global equity markets continued to make further modest progress in the third quarter, despite a more challenging backdrop of renewed Middle East tensions, higher energy prices and rising bond yields. While this was a more difficult environment for fixed income markets, the resilience of economic activity and healthy corporate earnings continued to support company shares, with enthusiasm for artificial intelligence (AI) and related infrastructure remaining an important driver of returns.
The renewed escalation of the Middle East conflict saw a significant increase in energy prices in the quarter, and this added to inflation concerns at a time when fiscal deficits and heavy government borrowing were already placing upward pressure on longer-term bond yields. The US Federal Reserve, European Central Bank and Bank of Japan all tightened monetary policy by raising interest rates during September. Despite the latest UK inflation data for August showing an increase to 3.1%, the Bank of England held bank rate at 3.75%, although markets expect a rise in the Bank Rate during the fourth quarter.
Despite these many potential headwinds for equity investors, their impact has been outweighed by the unexpected resilience of the global economy and accelerating corporate earnings growth, led by the energy and technology sectors.
UK equities have a sector mix that differs from other markets and can lag when technology stocks are leading the way, but strength in areas like energy and basic materials saw the UK FTSE All-Share index gain 2.4% in the third quarter of 2026, improving the 9-month return to 9.8%. International equities saw a smaller terms gain of 1.5%, in sterling terms in the third quarter resulting in a 9-month return of 14.5%. Japan saw the strongest returns on the quarter, and alongside Asia Pacific ex-Japan leads the way in 2026.
Performance Chart
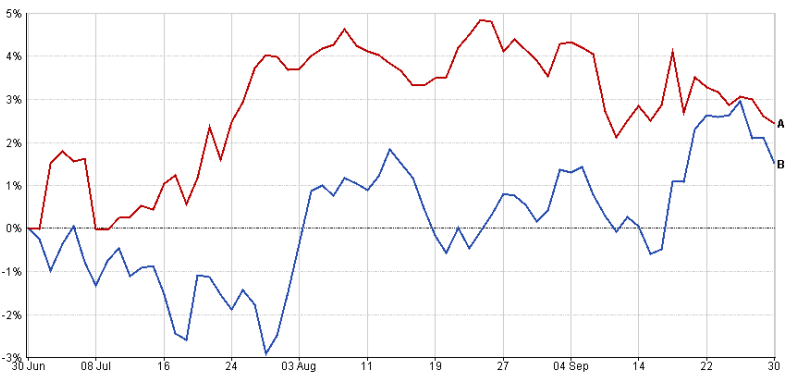
A - FTSE All Share TR in GB (2.44%)
B - FTSE All World ex UK TR in GB (1.51%)
| Name | 30/9/25 - 30/9/26 | 30/9/24 - 30/9/25 | 30/9/23 - 30/9/24 | 30/9/22 - 30/9/23 | 30/9/21 - 30/9/22 |
|
FTSE All Share TR in GB |
16.8 | 16.2 | 13.4 | 13.8 | -4.0 |
|
FTSE All World ex UK TR in GB |
18.3 | 16.9 | 20.0 | 10.4 | -4.3 |
Total return income reinvested. Pounds Sterling.
Data from FE fund info 2026
Outside of the challenges listed above for fixed income markets, there was additional focus on fiscal sustainability in France, and also in the UK as investors assessed the new political leadership and how they would address their fiscal issues. Government bonds saw widespread losses as yields in many countries hit their highest levels for many years. UK gilts fell by -2.5% in the third quarter, taking the 9-month return to -2.4%. There were also modest third quarter losses across our other fixed income categories, taking corporate bonds and emerging market debt into negative territory for 2026, leaving only high yield with a gain of 0.3%. Cash deposits have seen 9-month returns of around 2.8%.
Elevated gilt yields and geopolitical uncertainty have constrained UK commercial property valuations, but overall returns continued to be supported by income, rental growth and solid occupier demand across most sectors, with estimated 9-month market returns of around 3%. Overseas real estate has seen similar challenges and returns, while infrastructure markets have seen modest underlying growth, with relevant funds continuing to build their allocations alongside the latest addition of direct lending private debt.
Market Outlook
Key Takeaways
Investment markets enter the final quarter of 2026 balancing the positives of a resilient global economy and strong corporate earnings fuelled by investment in artificial intelligence and related infrastructure. Against this are the challenges of a volatile geopolitical backdrop, persistent inflation pressures, elevated government borrowing and bond yields, and some concerns about the scale of investment in AI and the growing dependency on it for growth. Although there are certainly risks that could see periods of elevated volatility across different asset classes, overall, the fundamental investment environment and valuation outlook remain broadly constructive, with diversification and retaining a disciplined long-term approach as important as ever in managing risks.
Background Investment Environment
The global economy and market sentiment have coped impressively well with the impact of higher energy prices and supply disruption, but geopolitical developments remain an ongoing source of uncertainty. Any renewed Middle East or other conflict escalation could create a fresh inflation shock and weaken sentiment, while a more durable de-escalation would allow markets to refocus on economic growth and corporate fundamentals.
Government finances are also receiving greater scrutiny, with elevated debt levels and ongoing budget deficits across much of the developed world. With growing demand for spending in areas like defence and increased competition for capital from companies borrowing to invest in AI infrastructure, the costs of governments’ substantial refinancing requirements have moved steadily higher. Investors are likely to require credible medium-term plans from governments, including the new UK leadership, that budget deficits are under control.
While political and geopolitical developments, fiscal sustainability, and the opportunities and risks from developments in AI tend to dominate the news headlines and can impact short-term market sentiment, history shows the importance of investors remaining focused on the key fundamental longer-term drivers such as economic and corporate growth, inflation, interest rates and the starting valuation of assets.
Economic and Rates Outlook
As always, there are pockets of relative strength and weakness such as headwinds from events in the Middle East and higher borrowing costs, but overall, the global economy continues to expand at a relatively robust rate of around 3%. A key factor supporting this economic resilience has been the significant spending on AI-related capital expenditure, especially in the US and parts of Asia. Despite some concerns over the scale of AI spending and potential risks, this spending is set to remain an important support for economic and corporate growth.
The inflation outlook is likely to remain the key influence on interest rates, and higher energy costs have reversed the previously anticipated scope for rate lowering. Core inflation (excluding food and energy) has encouragingly remained relatively under control, but many central banks have felt the need to react to higher overall inflation levels with tighter monetary policy and will be monitoring for signs of inflationary pressures broadening. The latest UK inflation rate is 3.1%, and the Bank of England has so far resisted raising Bank Rate, but with inflation set to move higher, markets are expecting a move this quarter. There are mixed views on how many rate rises may be needed to suppress inflation, but it is still hoped that increases will be relatively limited and the medium-term direction of rates should still be lower as inflation moderates.
Cash and Investments Mix
Cash continues to offer useful security, liquidity and healthier nominal returns since interest rates have returned to more normalised levels in recent years, making it a useful component of a diversified portfolio alongside other investments. The current UK Bank Rate of 3.75% is set to move higher in the short term, but over the medium to longer term cash can often fail to match inflation. Investors should seek to strike the optimal balance to suit their risk appetite, time horizon and growth objectives between cash and the superior long-term income and growth potential available from a suitably diversified mix of investment assets.
Fixed Income Assets (Bonds)
The rise in bond yields from the exceptionally low levels of the previous cycle has improved prospective returns and restored much of fixed income’s traditional ability to provide income and diversification within mixed asset portfolios. Government bonds now offer starting yields at levels not seen since before the 2008 global financial crisis, although investors will remain focused on the fiscal sustainability challenges many governments are facing and any risks to the inflation outlook. UK government bonds (gilts) offer a relatively high yield compared to other developed markets, but investor confidence will focus on credible economic and budgetary policy from the new leadership.
Corporate bonds, high yield and emerging market debt offer additional income to compensate investors for their greater potential risk. Company balance sheets remain generally sound and defaults are contained, but credit spreads (the additional yield over equivalent gilts) are tight by historic standards and leave little room for disappointment were conditions to deteriorate. However, after a challenging period we do see overall improved value in fixed income assets, with increased income levels in excess of 5% providing a useful cushion against any further capital weakness.
Equities (Company Shares)
Equities continue to be supported by resilient economic activity and very healthy corporate earnings growth, with energy, technology and other AI-related sectors remaining important contributors. Despite many markets being close to all-time highs, valuations have improved thanks to the strength of profits. The AI theme has become a dominant driver as exceptional levels of investment are being committed to building out the infrastructure to support AI. This capital expenditure cycle has plenty of room to run, with the next leg likely to also be driven by companies adopting AI to drive efficiency gains and new growth. AI certainly has the potential to be a significant multi-year theme for markets, but with expectations already high and concerns about emerging risks being identified there is a danger of disappointment on any signs of growth slowing or a lack of sufficient returns from the substantial investment being made. This creates scope for both further gains and periods of disappointment as expectations are tested.
The US retains a leading position in technology, helping support its economy, but market leadership has broadened beyond the largest US tech companies, and other markets also contain significant technology exposures in Asia while also offering useful diversification to other themes. The US retains powerful structural advantages, including innovative companies, deep capital markets, a large domestic economy and energy independence, but valuations remain relatively elevated. Europe, Japan and emerging markets offer different sector exposures and, in many cases, more attractive valuations, supporting a geographically diversified approach to complement a still significant US exposure.
UK equities have faced some structural headwinds in recent years such as persistent investor outflows, a subdued domestic economy, and a limited exposure to listed technology stocks. However, valuation and dividend income levels remain attractive compared to other markets, as recognised by ongoing takeover interest from overseas buyers and private equity. The UK market also contains a broad range of multinational and domestic companies with a differentiated sector mix, that could benefit from investors considering greater diversification beyond markets heavily exposed to AI.
Private Assets (less liquid assets that are not publicly traded)
The outlook for UK real estate remain constrained by prevailing bond yields and geopolitical uncertainty. Capital values are expected to see further declines in the final quarter, although the underlying occupier picture remains resilient in most areas. Income will remain the main driver of returns, with the 2026 market total return now expected to be around 4%. Overseas real estate and infrastructure allocations continue to be established in appropriate portfolios alongside the latest addition of private debt, with the expectation that they will provide additional diversified sources of returns over time.
Conclusion
Market sentiment looks set to continue to be dominated by the key themes of AI, fiscal sustainability, the impact of ongoing conflicts, and the resilience of the global economy and strength of corporate earnings.
Fixed income assets have struggled in recent years, and challenges remain, but the much-improved income levels suggest they are now closer to fair value relative to equities for the first time in many years. Equities are becoming increasingly reliant on the continuation of rapid AI growth, and its significant potential will need to be delivered to justify related valuations, but on balance equities look set to continue to benefit from healthy corporate earnings which have made valuations more attractive across most markets.
Overall, we remain broadly constructive on the outlook for diversified investment portfolios and their potential to offer superior longer-term returns compared to cash, while recognising the risk of periods of shorter-term volatility. Maintaining a disciplined and balanced approach across asset classes, sectors and regions helps manage risks, and investors should aim to stay focused on the longer-term attractions of remaining invested through any periods of short-term uncertainty.
Paul Glover
Chief Investment Manager
October 2026
Please remember that past performance is not a reliable indicator of future results. The value of investments and the level of income received from them can fall as well as rise, and is not guaranteed.
You may not get back the amount of your original investment.
NFU Mutual Financial Advisers advise on NFU Mutual products and selected products from specialist providers. When you contact us we'll explain the advice services we offer and the charges. Financial advice is provided by NFU Mutual Select Investments Limited.
Looking for financial advice?
If you’re not sure how to put your financial plan in place we can help. An NFU Mutual Financial Adviser will recommend products that are right for you based upon your personal circumstances. You can book an appointment with an NFU Mutual Financial Adviser by either calling: 0800 622 323 or requesting a call back.