Home Insurance
How much contents insurance do you really need?
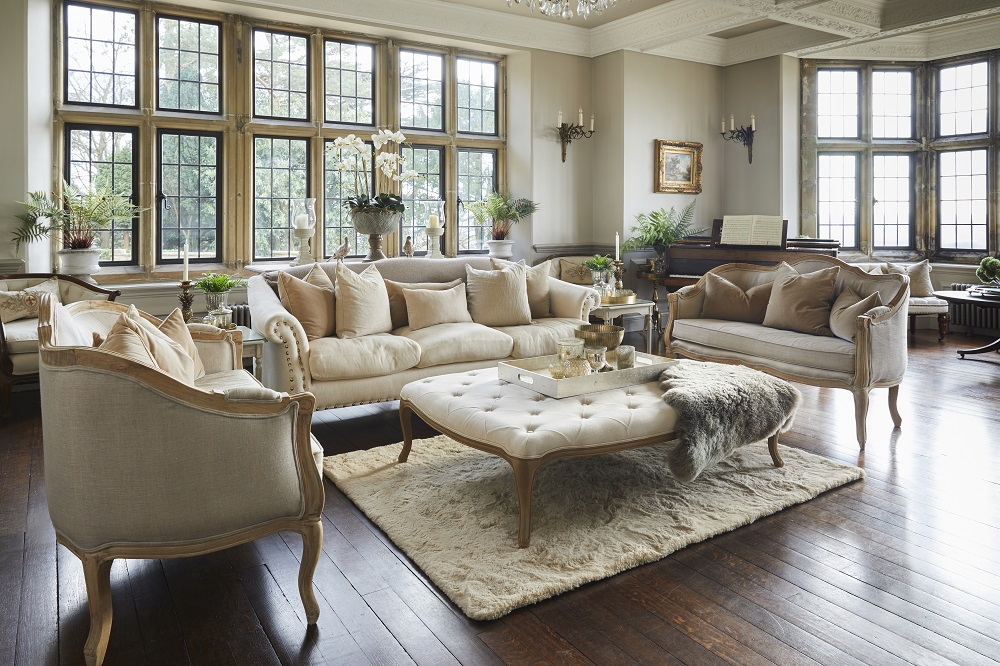
Are you sure you're insured for the true value of everything you own?
Knowing how much contents insurance you need isn't always straightforward. Many people underestimate the value of their belongings, leaving themselves at risk of being underinsured if they ever need to make a claim.
From furniture and technology to jewellery, artwork and family heirlooms, the cost of replacing everything in your home can be much higher than expected. Taking the time to calculate the value of your home contents can help ensure you have the right level of cover in place.
How much contents insurance do I need?
The amount of contents insurance you need should reflect the total cost of replacing all your possessions with new equivalents.
This includes everyday items such as furniture, carpets, curtains, clothing, kitchen appliances, and technology, as well as valuable possessions like jewellery and watches, fine art and collections.
Many people are surprised by how quickly the value of their belongings adds up. While individual items may not seem particularly expensive on their own, replacing everything at once after a fire, flood or burglary could cost significantly more than expected.
What does being underinsured mean?
To be underinsured means that the amount you're covered for is less than the actual cost of rebuilding, replacing or repairing your property and belongings.
For example, if you had a fire at home and the value of your contents was declared as £150,000, but the true replacement cost was £225,000, you'd be underinsured. This could leave you receiving less than the full value of your claim and having to cover the shortfall yourself.
Why an accurate home contents valuation matters
When choosing high value home insurance, it's important to look beyond convenience or cost and consider the true value of everything you own.
Alastair Meiklejon from Doerr Dallas Valuations recalls a case involving a substantial estate inherited by a prominent farming family. The contents had last been valued in the 1990s and adjusted only for inflation, resulting in an estimated value of approximately £250,000. Following a professional valuation, the true value of the contents was found to be £721,000.
This highlights the importance of regularly reviewing your contents valuation, particularly if you own antiques, artwork, jewellery, watches or other high-value possessions.
How to calculate the value of your home contents
To avoid underinsurance, consider the following steps:
1. Get an up-to-date valuation
At NFU Mutual, we work with trusted valuation partners who can, for a fee, provide professional valuations of your home and contents.
2. Create a room-by-room inventory
Account for everything in each room, including:
- furniture
- soft furnishings
- curtains and carpets
- electrical items
- clothing
- decorative items
- jewellery and watches.
Don't forget garages, lofts, outbuildings, and storage locations.
3. Use replacement costs, not purchase prices
Estimate what it would cost to replace each item with a new equivalent today, rather than what you originally paid for it.
4. Reassess antiques, artwork, and collections regularly
The value of antiques, fine art and collectables can change significantly over time. Regular valuations can help ensure they remain appropriately insured.
5. Include items stored away from home
Items held in storage units, bank vaults, safes or other secure locations should still be included within your contents valuation.
6. Review policy limits for valuable items
Check whether your policy includes limits for individual valuables and understand how higher-value possessions are covered.
For assistance in getting started, you can use our interactive contents calculator tool.
What should be included in a home contents valuation?
A common mistake is overlooking everyday possessions.
Your contents valuation should typically include:
- furniture and furnishings
- carpets, curtains and rugs
- clothing and footwear
- TVs, laptops and electronic devices
- kitchen appliances
- jewellery and watches
- artwork and antiques
- collections and memorabilia
- books and hobby equipment
- garden furniture
- sports equipment
- items stored in garages, lofts, sheds and storage facilities.
As a general rule, if you would take the item with you when moving house, it is likely to form part of your contents valuation.
High-value possessions need special consideration
For those living in larger homes or owning valuable possessions, standard home insurance policies may not always provide comprehensive protection.
Items such as:
- jewellery and watches
- fine art
- antiques
- wine collections
- collectables
- inherited valuables
can require more specialist consideration.
Some policies may not include features such as agreed value cover or access to specialist repair, restoration or replacement services that are important when protecting valuable assets.
Regular valuations can also help ensure insurance reflects current market values.
Review your insurance cover regularly
The best way to avoid underinsurance is to review your cover regularly.
It’s particularly important to revisit your valuation:
- at renewal
- following a major purchase
- after receiving valuable gifts
- after inheriting valuable possessions
- following home improvements
- when market values change significantly.
Insurance may not be the first thing on your mind after receiving a special birthday or Christmas gift, but taking a few minutes to review your cover could help prevent costly surprises later.
Speaking with an expert can be invaluable when valuing your home and possessions. While buying insurance online may seem quick and convenient, professional guidance can help ensure your cover reflects the true value of everything you own.
We offer a nationwide network of local agency offices, providing a personal service tailored to your circumstances. We work with trusted partners who can, for a fee, provide valuations on your home and contents.
Frequently Asked Questions
Is £50,000 enough contents insurance?
It depends entirely on the value of your belongings. For some households, £50,000 may be enough. For others, particularly those with valuable jewellery, artwork, collectables or technology, it may be insufficient.
The most reliable approach is to calculate the replacement value of everything you own rather than relying on average figures.
How often should I review my contents insurance?
You should review your contents valuation at least annually and whenever you make significant purchases, inherit valuables or undertake major home improvements.
What happens if I'm underinsured?
If the value of your belongings exceeds the amount you're insured for, you may not receive enough from a claim to cover the full replacement cost of your possessions.
Do I need professional valuations for jewellery, artwork and antiques?
Professional valuations can help provide a more accurate assessment of high-value possessions and may help ensure they are insured appropriately.
NFU Mutual High-Value Home Insurance
NFU Mutual High-Value Home Insurance is designed for larger homes and valuable possessions that may require more tailored protection than a standard home insurance policy.
Designed for homes with contents valued at more than £150,000, our cover can help protect valuable possessions such as jewellery, watches, fine art, antiques, and collections.
Tailored around you and your lifestyle, our cover helps provide reassurance that your most valuable possessions are in safe hands.